Search This Blog

Monday, April 5, 2021

SoCal, Your Tax Refund and Stimulus Savings May Help

SoCal, Your Tax Refund and Stimulus Savings May Help: If you’re planning to buy a home this year, saving for a down payment is one of the most important steps in the process. One of the best ways to jumpstart.......By 
Your Tax Refund and Stimulus Savings May Help You Achieve Homeownership This Year | MyKCM

If you’re planning to buy a home this year, saving for a down payment is one of the most important steps in the process. One of the best ways to jumpstart your savings is by starting with the help of your tax refund.

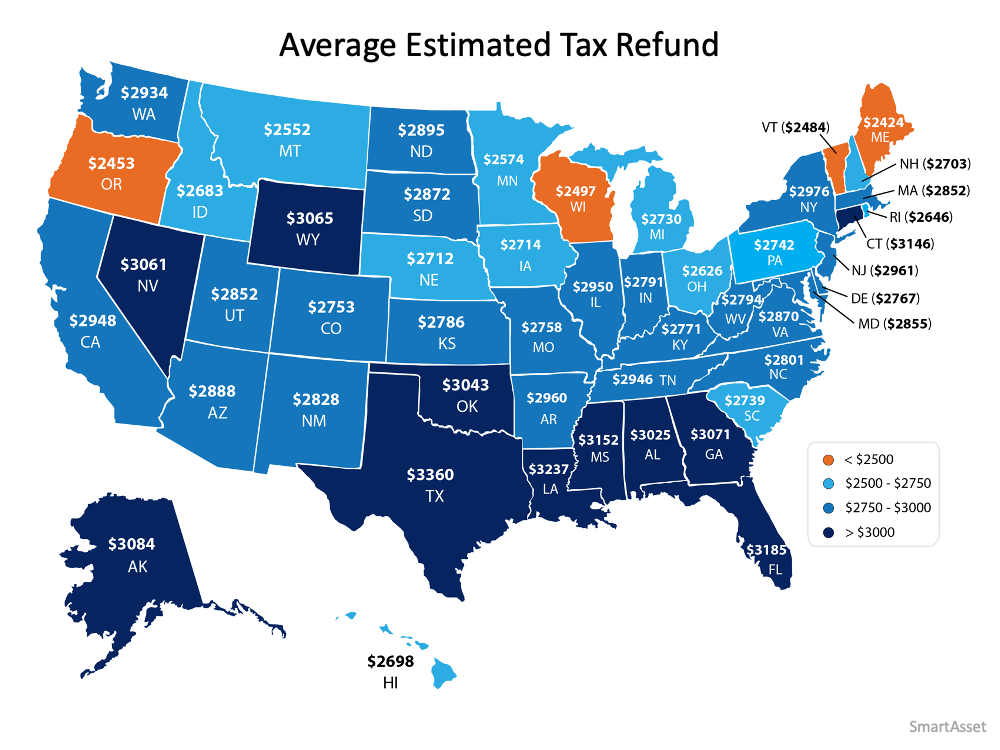
Using data from the Internal Revenue Service (IRS), it’s estimated that Americans can expect an average refund of $2,925 when filing their taxes this year. The map below shows the average anticipated tax refund by state:Your Tax Refund and Stimulus Savings May Help You Achieve Homeownership This Year | MyKCMThanks to programs from the Federal Housing Authority, Freddie Mac, and Fannie Mae, many first-time buyers can purchase a home with as little as 3% down. In addition, Veterans Affairs Loans allow many veterans to put 0% down. You may have heard the common myth that you need to put 20% down when you buy a home, but thankfully for most homebuyers, a 20% down payment isn’t actually required. It’s important to work with your real estate professional and your lender to understand all of your options.
How can your tax refund help?

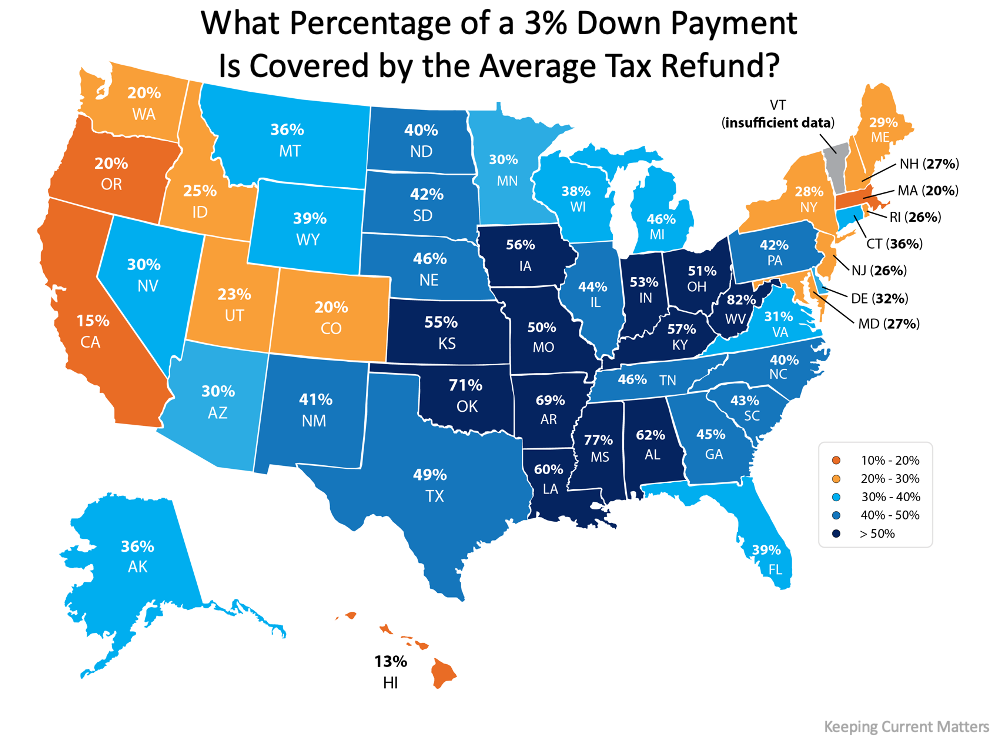
If you’re a first-time buyer, your tax refund may cover more of a down payment than you realize.

If you take into account the median home sale price by state, the map below shows the percentage of a 3% down payment that’s covered by the average anticipated tax refund:Your Tax Refund and Stimulus Savings May Help You Achieve Homeownership This Year | MyKCMThe darker the blue, the closer your tax refund gets you to homeownership when you qualify for one of the low down payment programs. Maybe this is the year to plan ahead and put your tax refund toward the down payment on a home.
Not enough money from your tax return? 

A recent paper from the National Bureau of Economic Research found that, of the households that received a stimulus check last year, “One third report that they primarily saved the stimulus money.” If you had the opportunity to save your Economic Impact Payments, you may consider putting that money toward your down payment or closing costs as well. Your trusted real estate professional can also advise you on the down payment assistance programs available in your area.

Bottom Line

Saving for a down payment can seem like a daunting task, but it doesn’t have to be. This year, your tax refund and your stimulus savings could add up big when it comes to reaching your homeownership goals.



The information contained, and the opinions expressed, in this article are not intended to be construed as investment advice. Keeping Current Matters, Inc. does not guarantee or warrant the accuracy or completeness of the information or opinions contained herein. Nothing herein should be construed as investment advice. You should always conduct your own research and due diligence and obtain professional advice before making any investment decision. Keeping Current Matters, Inc. will not be liable for any loss or damage caused by your reliance on the information or opinions contained herein.
 
Post a Comment

Friday, April 2, 2021

SoCal Buyer Competition Is Good News for Sellers [INFOG

SoCal Buyer Competition Is Good News for Sellers [INFOG: With so many buyers looking for homes to purchase and so few houses available today, there’s a substantial increase in bidding wars, and home #TimeToSell..........................   By 
Buyer Competition Is Good News for Sellers [INFOGRAPHIC] | MyKCM

Some Highlights

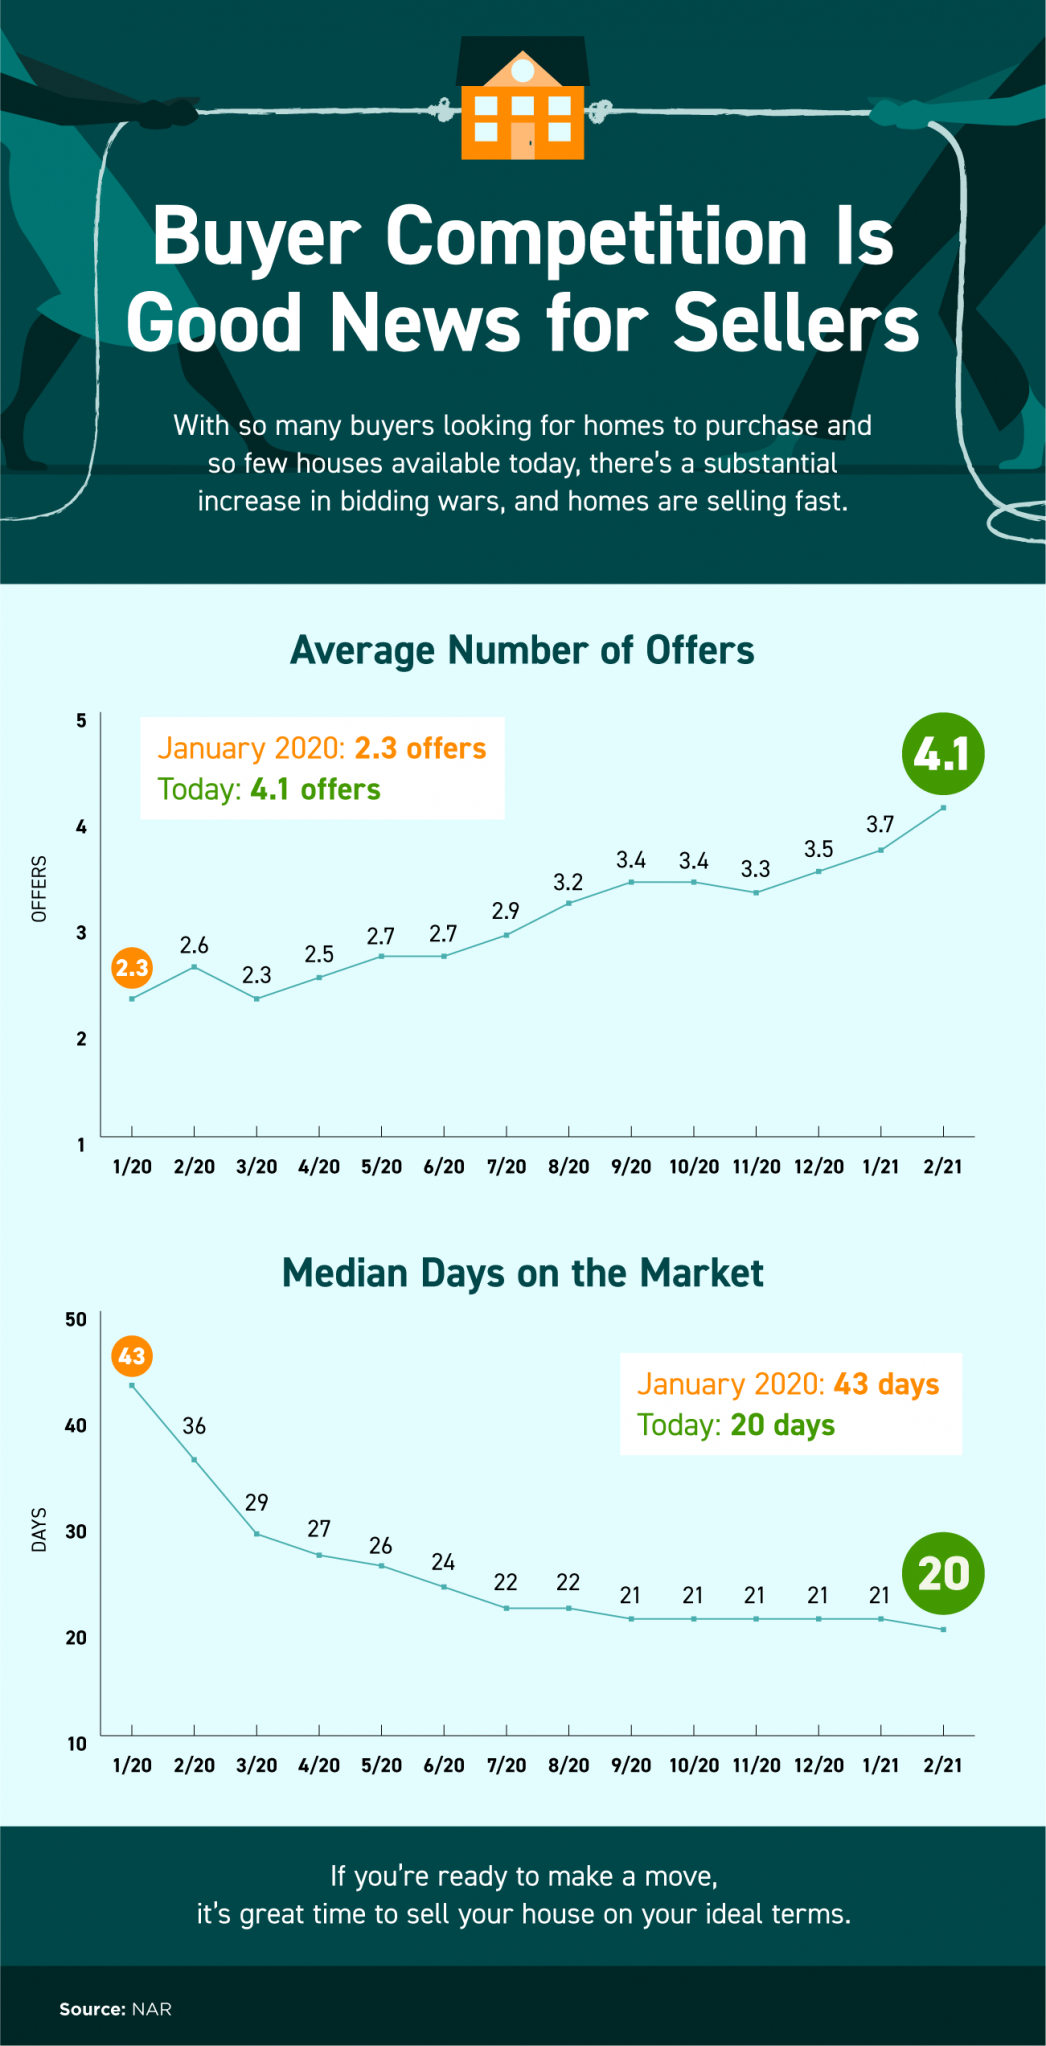
  • With so many buyers looking for homes to purchase and so few houses available today, there’s a substantial increase in bidding wars, and homes are selling fast.
  • According to the latest Realtors Confidence Index Survey from the National Association of Realtors (NAR), on average, houses are receiving over four offers from buyers and they’re selling in less than three weeks.
  • If you’re ready to make a move, let’s connect today so you can sell your house while the market is in your favor.


The information contained, and the opinions expressed, in this article are not intended to be construed as investment advice. Keeping Current Matters, Inc. does not guarantee or warrant the accuracy or completeness of the information or opinions contained herein. Nothing herein should be construed as investment advice. You should always conduct your own research and due diligence and obtain professional advice before making any investment decision. Keeping Current Matters, Inc. will not be liable for any loss or damage caused by your reliance on the information or opinions contained herein.
 
Post a Comment

https://youtu.be/p4-VfR1DJNA

https://youtu.be/CRCXLh4EycU

https://www.ratemyagent.com/real-estate-agent/chris-b-johnson-xu316/reviews

http://www.VCNeighborhoodValues.com

http://www.ChrisBJohnsonRealtor.AllisonJamesInc.com/blog.php

http://www.ChrisBJohnsonRealtor.AllisonJamesInc.com/

https://ajirealestate.com/chris-johnson/  

http://my.flexmls.com/ChrisBJohnsonRealtor

https://www.idealestate.co/profile/76080/profile

https://www.simplifyingthemarket.com/en/?a=97822-26df5ea08f8689012df0225866ae0bf1

https://www.linkedin.com/today/author/chrisbjohnson

https://www.linkedin.com/in/chrisbjohnson/detail/recent-activity/posts/

https://www.linkedin.com/pro/chrisbjohnson

http://www.linkedin.com/in/chrisbjohnson

https://activerain.com/profile/chrisbjohnson

https://activerain.com/blogs/chrisbjohnson

https://www.youtube.com/c/ChrisBJohnsonRealtor

http://chrisbjohnsonrealtorluxuryhomes.blogspot.com/

https://chris-b-johnson-realtor.business.site

https://moorpark-short-sale-specialist.business.site

http://www.ChrisBJohnsonRealtor.com

http://www.twitter.com/CBJRealtor

https://www.pinterest.com/chrisbjohnsonre/

https://www.instagram.com/chrisbjohnsonrealtor/

https://www.facebook.com/VenturaCountyEstateShortSaleBankOwnedRealtor/

http://www.facebook.com/MoorparkShortSaleSpecialist

http://www.facebook.com/StopForeclosureVenturaCounty

https://www.bidonhomes.com/propertydetail/139?fbclid=IwAR1Rf_fH0seFuqJNg5X9TtFNTw-FaPxXf87SpcNalS1kbLlV_qJDeIKK8o0


REALTOR®, IREM® CPM®-Candidate, Certified Xome Luxury

Home Auction, REO, Probate & Short Sale Specialist at AJElite

Los Angeles & Ventura County Metropolitan Areas. Certified by the National Association of Realtors as a Short Sale and Foreclosure Resource, and Broker Price Opinion Resource. I am a Member of, and Certified by the California Association of Realtors as a Certified Home Affordable Foreclosure Alternative Specialist. I am a Certified Distressed Property Expert, Certified Short Sale Negotiator, Certified Pre-Foreclosure Specialist and Certified Default Advocate. Certified REO Agent with; Equator #1178236, RESNET # 45083, Xome #PMTier6 SPS-PMH #35810


Thursday, April 1, 2021

There is No Reason To Worry Over Today’s SoCal Lending

There is No Reason To Worry Over Today’s SoCal Lending: Today, some are afraid the real estate market is starting to look a lot like it did in 2006, just prior to the housing crash. One of the factors they’re .........
There’s No Reason To Panic Over Today's Lending Standards | MyKCM

Today, some are afraid the real estate market is starting to look a lot like it did in 2006, just prior to the housing crash. One of the factors they’re pointing to is the availability of mortgage money. Recent articles about the availability of low down payment loans and down payment assistance programs are causing fear that we’re returning to the bad habits seen 15 years ago. Let’s alleviate these concerns.

Several times a year, the Mortgage Bankers Association releases an index titled The Mortgage Credit Availability Index (MCAI). According to their website:

“The MCAI provides the only standardized quantitative index that is solely focused on mortgage credit. The MCAI is…a summary measure which indicates the availability of mortgage credit at a point in time.”

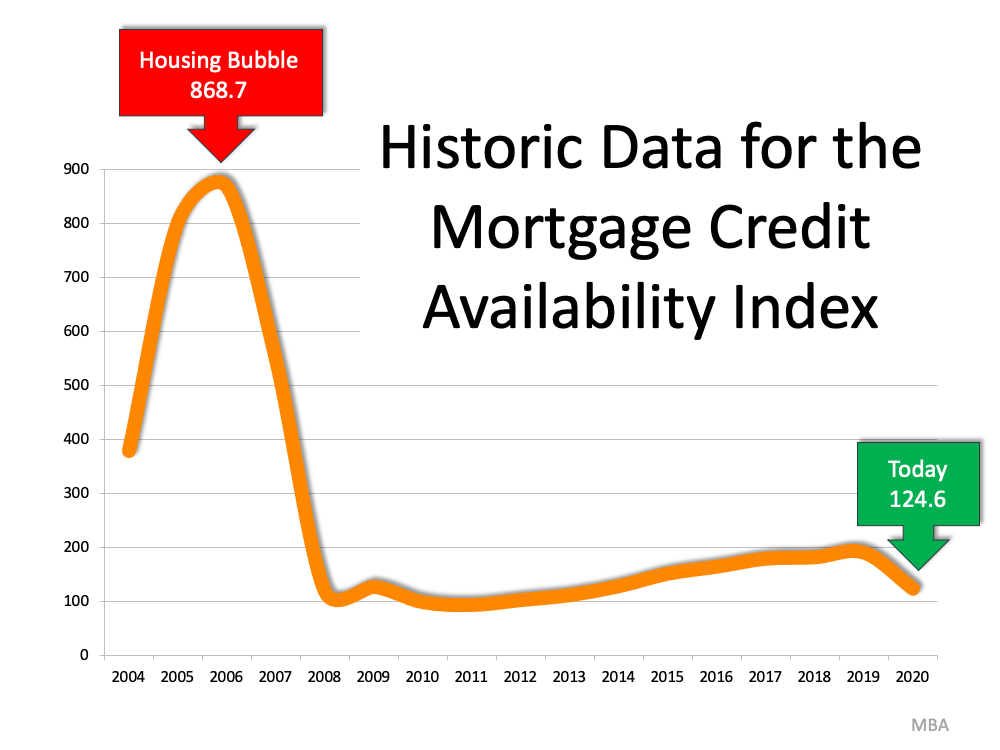
Basically, the index determines how easy it is to get a mortgage. The higher the index, the more available mortgage credit becomes. Here’s a graph of the MCAI dating back to 2004, when the data first became available:There’s No Reason To Panic Over Today's Lending Standards | MyKCMAs we can see, the index stood at about 400 in 2004. Mortgage credit became more available as the housing market heated up, and then the index passed 850 in 2006. When the real estate market crashed, so did the MCAI (to below 100) as mortgage money became almost impossible to secure. Thankfully, lending standards have eased somewhat since. The index, however, is still below 150, which is about one-sixth of what it was in 2006.

Why did the index rage out of control during the housing bubble?

The main reason was the availability of loans with extremely weak lending standards. To keep up with demand in 2006, many mortgage lenders offered loans that put little emphasis on the eligibility of the borrower. Lenders were approving loans without always going through a verification process to confirm if the borrower would likely be able to repay the loan.

Some of these loans offered attractive, low interest rates that increased over time. The loans were popular because they could be obtained quickly and without the borrower having to provide documentation up front. However, as the rates increased, borrowers struggled to pay their mortgages.

Today, lending standards are much tighter. As Investopedia explains, the risky loans given at that time are extremely rare today, primarily because lending standards have drastically improved:

“In the aftermath of the crisis, the U.S. government issued new regulations to improve standard lending practices across the credit market, which included tightening the requirements for granting loans.”

An example of the relaxed lending standards leading up to the housing crash is the FICO® credit score associated with a loan. What’s a FICO® score? The website myFICO explains:

“A credit score tells lenders about your creditworthiness (how likely you are to pay back a loan based on your credit history). It is calculated using the information in your credit reports. FICO® Scores are the standard for credit scores—used by 90% of top lenders.”

During the housing boom, many mortgages were written for borrowers with a FICO score under 620. Experian reveals that, in today’s market, lenders are more cautious about lower credit scores:

“Statistically speaking, 28% of consumers with credit scores in the Fair range are likely to become seriously delinquent in the future…Some lenders dislike those odds and choose not to work with individuals whose FICO® Scores fall within this range.”

There are definitely still loan programs that allow a 620 score. However, lending institutions overall are much more attentive about measuring risk when approving loans. According to Ellie Mae’s latest Origination Insight Report, the average FICO® score on all loans originated in February was 753.

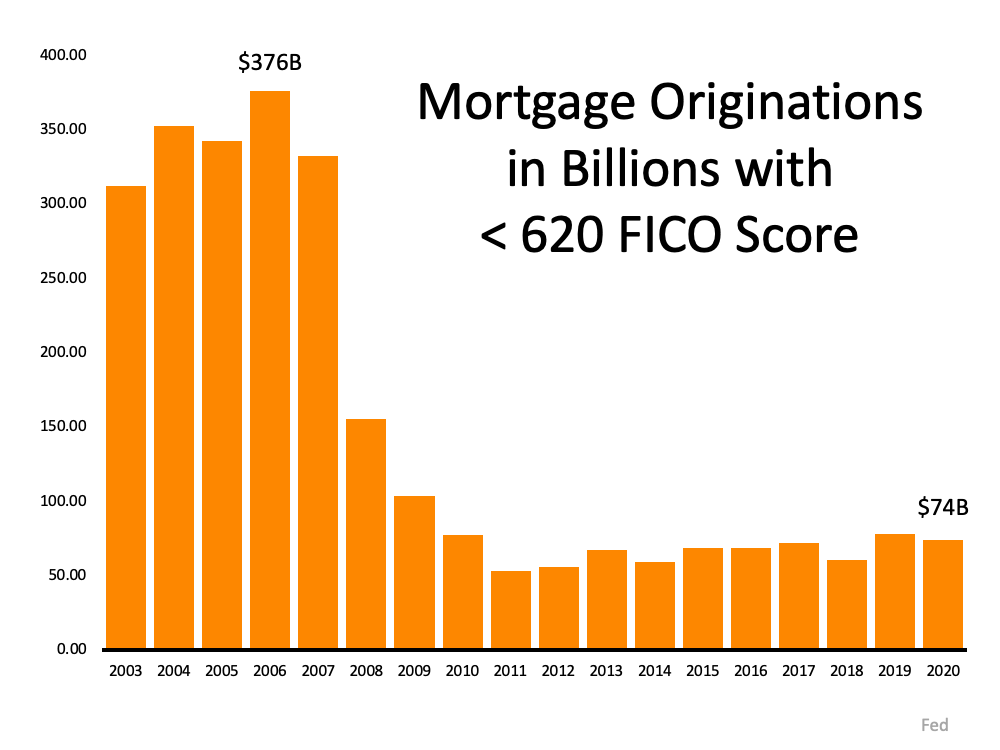
The graph below shows the billions of dollars in mortgage money given annually to borrowers with a credit score under 620.There’s No Reason To Panic Over Today's Lending Standards | MyKCMIn 2006, mortgage entities originated $376 billion dollars in loans for purchasers with a score under 620. Last year, that number was only $74 billion.

Bottom Line

In 2006, lending standards were much more relaxed with little evaluation done to measure a borrower’s potential to repay their loan. Today, standards are tighter, and the risk is reduced for both lenders and borrowers. These are two very different housing markets, so there’s no need to panic over today’s lending standards.


The information contained, and the opinions expressed, in this article are not intended to be construed as investment advice. Keeping Current Matters, Inc. does not guarantee or warrant the accuracy or completeness of the information or opinions contained herein. Nothing herein should be construed as investment advice. You should always conduct your own research and due diligence and obtain professional advice before making any investment decision. Keeping Current Matters, Inc. will not be liable for any loss or damage caused by your reliance on the information or opinions contained herein.
 
Post a Comment